Book Summary | Personal Finance | Financial Freedom | Wealth Building | Money Management | Personal Development
What if becoming financially free didn’t require a complicated investment strategy—but simply a better system for managing the money you already earn?
For years, many people believe that financial freedom begins when they start earning a lot more money.
But what if the real beginning is much simpler?
Knowing exactly where your money goes.
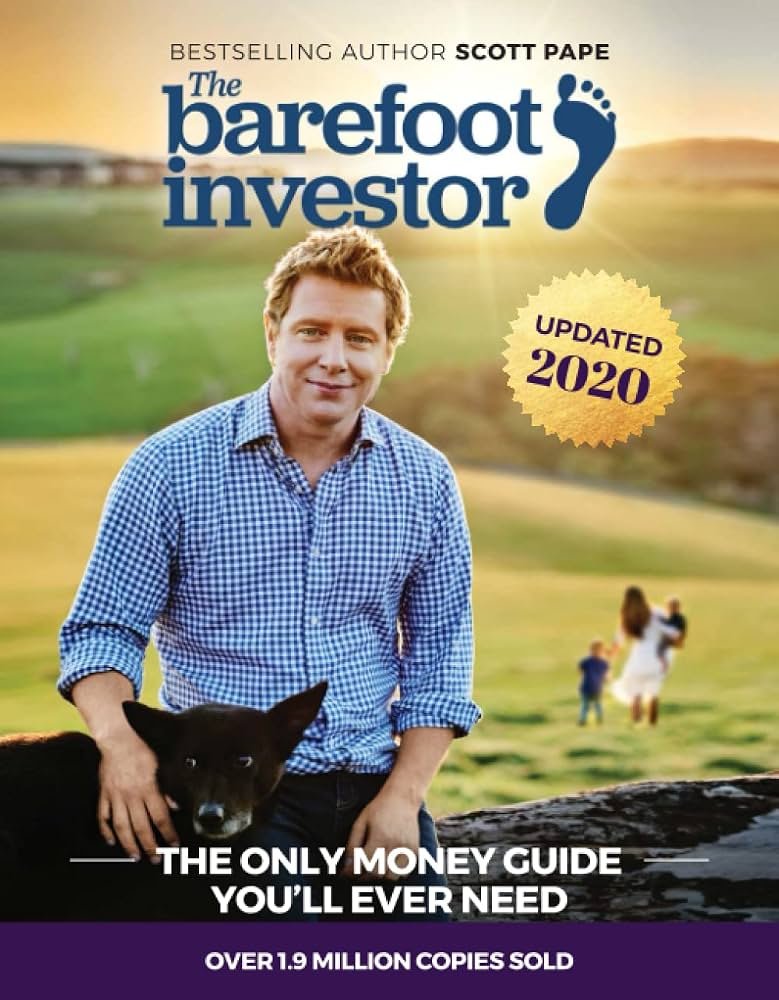
That is the central appeal of The Barefoot Investor by Scott Pape.
A small correction before we begin: the widely published title is The Barefoot Investor: The Only Money Guide You’ll Ever Need, and the author is Scott Pape, not “Wisly.” I’m using the book’s correct title and author below. Scott Pape’s official website presents the system as nine sequential “Barefoot Steps,” beginning with a monthly money conversation and setting up buckets, then moving through debt, home ownership, superannuation, emergency savings, mortgage reduction, retirement and legacy.
What makes the book different is that it doesn’t begin with complicated financial theory.
It begins with ordinary life.
Bills.
Debt.
Shopping.
Relationships.
Savings.
Home loans.
Retirement.
And the uncomfortable question almost everyone eventually has to answer:
“Am I actually in control of my money?”
This blog explores the major ideas behind The Barefoot Investor and shows how those ideas can become practical habits rather than remaining lessons trapped inside a book.
Disclaimer: This article is an educational summary and interpretation of the book’s concepts, not personalized financial advice. The original book is written primarily for the Australian financial environment, so readers in India or other countries should adapt concepts such as superannuation, taxation, home loans and investment accounts to their own country’s rules and seek appropriate professional advice when necessary.
Why The Barefoot Investor Matters
Imagine two people earning exactly the same salary.
One earns ₹1,00,000 a month and spends almost everything.
The other earns ₹1,00,000 and deliberately gives every rupee a purpose.
After five years, their financial lives can look completely different.
The difference isn’t necessarily income.
It is behavior and structure.
Scott Pape’s approach tries to remove some of the complexity from personal finance by creating a system in which money automatically moves toward spending, enjoyment, safety and long-term wealth.
His official “Barefoot Steps” currently describe nine stages of the system, from setting up the household money routine and buckets to eliminating debt, building emergency savings, reducing the mortgage, planning retirement and leaving a legacy.
The philosophy is particularly useful for people who:
- earn a reasonable income but never seem to have enough
- struggle with budgeting
- have consumer debt
- want to build an emergency fund
- want to invest for the future
- feel overwhelmed by financial terminology
- want a simple money-management system
- want financial independence without obsessing over money every day
The Story Behind the Strategy: Money Should Have a Job
Scott Pape explains that his household money system was designed to be so simple that it could be drawn on the back of a restaurant serviette.
The system divides money into three major buckets:
- Blow — everyday spending and expenses
- Mojo — safety and emergency savings
- Grow — long-term wealth building
Within the broader system are accounts such as Splurge, Smile and Fire Extinguisher, each with a different purpose.
The brilliance isn’t the names.
The brilliance is the separation.
When all your money sits in one account, everything looks spendable.
When money is separated according to purpose, your behavior can change.
Lesson 1: Have a “Barefoot Date Night”
The first step is surprisingly human.
Talk about money.
Pape’s first official Barefoot Step is to schedule a monthly “Barefoot Date Night” and use that time to put the financial system in place and have important money conversations.
Why does this matter?
Because money isn’t just mathematics.
Money affects relationships.
Partners may have different spending habits.
One person may love saving.
The other may enjoy spending.
One may want to buy a home.
The other may prioritize travel.
Without communication, these differences can quietly become conflicts.
A regular financial conversation creates a shared destination.
Practical tip
Once a month, sit down with your partner or family and discuss:
- income
- expenses
- debt
- savings
- upcoming large expenses
- financial goals
- progress
- one financial improvement for the next month
Don’t make the meeting feel like a punishment.
Have coffee.
Go for dinner.
Take a walk.
The goal is to make money management a normal part of life.
Lesson 2: Set Up Your Money Buckets
This is probably the most recognizable concept in The Barefoot Investor.
Pape’s official explanation divides household finances into:
1. Blow Bucket
This handles everyday expenses and spending.
2. Mojo Bucket
This provides safety money.
3. Grow Bucket
This is designed for long-term wealth.
Pape says he and his wife used the strategy for goals including saving for their honeymoon, paying off their mortgage, managing a business with uneven income and building emergency savings. He also says people across different ages and income levels have used the system.
The important idea is:
Don’t let every rupee sit in one giant pool.
Give money different jobs.
The Splurge Account: Why Enjoying Money Is Part of the Plan
One of the most interesting ideas is that financial discipline doesn’t have to mean eliminating enjoyment.
The system deliberately creates room for Splurge money.
Why?
Because a budget that says:
“You can never enjoy your money.”
usually becomes difficult to maintain.
Instead:
Save seriously. Spend intentionally. Enjoy some of your money without guilt.
That creates psychological balance.
Financial freedom isn’t supposed to become financial punishment.
The Smile Account: Save for Things That Make You Happy
The Smile account is designed for larger goals that take time to save for.
Perhaps:
- a holiday
- a wedding
- a major purchase
- a family experience
- another meaningful goal
Pape’s earlier explanation of the system describes Smile as money set aside for larger future expenses rather than everyday spending.
This changes the emotional experience of saving.
Instead of saying:
“I can’t afford this.”
you can say:
“I’m saving for this.”
That is a completely different mindset.
Lesson 3: Use the Fire Extinguisher to Attack Financial Problems
The Fire Extinguisher is designed for financial fires.
And financial fires are different at different stages of life.
They might include:
- credit-card debt
- personal loans
- saving for a home deposit
- other major financial obligations
- eventually mortgage reduction
- later, retirement goals
Pape explains that the Fire Extinguisher’s purpose changes as the household moves through different financial stages.
This is a powerful idea:
Your money system should evolve as your problems disappear.
First, extinguish the fire.
Then build security.
Then build wealth.
Lesson 4: Attack Debt Like a Domino Game
Pape calls the third major Barefoot Step “Domino Your Debts.”
Debt can feel overwhelming because it is abstract.
You may have:
- credit-card debt
- personal loans
- car loans
- education-related debt
- other obligations
Instead of looking at the entire mountain, the Barefoot philosophy encourages turning debt repayment into a sequence.
One debt falls.
Then another.
Then another.
Each victory creates momentum.
Practical approach
Make a complete debt list:
| Debt | Balance | Interest Rate | Minimum Payment |
|---|---|---|---|
| Credit Card | ₹___ | ___% | ₹___ |
| Personal Loan | ₹___ | ___% | ₹___ |
| Car Loan | ₹___ | ___% | ₹___ |
Then create a clear repayment strategy appropriate to your circumstances.
The exact best method can depend on interest rates and personal circumstances, but the behavioral principle is universal:
Make debt visible. Make progress visible. Keep going.
Real-Life Example 1: A Reader Who Paid Off Debt and Started Saving Again
Scott Pape’s official website features a reader story from someone who said they had spent more than $100,000 on personal-development courses and accumulated $50,000 in personal loans.
After following the Barefoot steps over several years, the reader reported paying off the debt and accumulating $50,000 in savings toward a future home deposit.
The important lesson isn’t the exact dollar figures.
It is the transformation.
The person moved from:
consumption → debt → financial stress
toward:
discipline → debt repayment → savings → future options
That’s exactly what a good financial system is supposed to do.
Lesson 5: Buy Your Home Carefully
Home ownership is a major part of the Barefoot sequence.
The official Step 4 is “Buy Your Home.”
But the deeper lesson isn’t simply:
“Everyone must buy a house.”
The important idea is to make housing decisions intentionally.
A home can provide stability.
But it can also become a financial burden if someone takes on more debt than they can comfortably manage.
Before purchasing property, consider:
- affordability
- down payment
- interest rates
- maintenance
- insurance
- taxes
- job stability
- location
- long-term plans
The right home is not necessarily the biggest home you can qualify for.
It is the home that fits your financial life.
Lesson 6: Invest for the Long Term
Once immediate financial fires are controlled, attention can shift toward long-term wealth.
The official Barefoot sequence eventually moves toward the Grow bucket and long-term wealth creation.
This is important because saving and investing serve different purposes.
Savings provide liquidity and safety.
Investing is about putting capital to work over the long term.
The right investment strategy depends on:
- age
- goals
- time horizon
- risk tolerance
- tax environment
- country
- financial situation
The Barefoot philosophy is less about becoming a brilliant stock picker and more about creating a system that steadily moves money toward future wealth.
Lesson 7: Build Your Mojo
The Mojo Bucket is the safety component of the system.
Pape’s official Step 6 recommends building Mojo to three months of living expenses.
Think about what happens when life suddenly changes.
A job disappears.
A family emergency occurs.
A major repair is required.
Income temporarily falls.
Without savings, people often turn to debt.
With savings, they have options.
That is why an emergency fund is not simply a financial number.
It is psychological security.
Pape’s explanation describes savings as creating freedom because having money set aside gives people greater control over their choices.
Lesson 8: Get the Banker Off Your Back
The seventh Barefoot Step is “Get the Banker Off Your Back.”
In simple terms, this means systematically reducing mortgage debt.
A mortgage can be useful because it allows people to purchase property without having the full amount in cash.
But debt also creates obligations.
Every monthly payment represents future income already committed.
Reducing that obligation can create greater financial flexibility.
Again, the exact approach should depend on interest rates, tax rules, investment opportunities and personal circumstances.
But the principle is powerful:
Don’t automatically assume debt must remain part of your life forever.
Lesson 9: Know Your Retirement Number
Many people say:
“I want to retire comfortably.”
But what does “comfortably” mean?
₹50,000 a month?
₹1 lakh?
₹2 lakh?
More?
The Barefoot system encourages people to think about a specific retirement target. Its official Step 8 is “Nail Your Retirement Number.”
This changes retirement from a vague dream into a financial planning problem.
Ask:
- When do I want financial independence?
- What lifestyle do I want?
- How much might I spend?
- What income sources will I have?
- How much should I invest?
- What assumptions am I making about inflation and returns?
You don’t need perfect answers.
You need a starting point.
Lesson 10: Leave a Legacy
The final official Barefoot Step is:
“Leave a Legacy.”
And this is where the book becomes bigger than budgeting.
What is wealth for?
Only for buying things?
Only for retirement?
Only for accumulating a larger number?
Or can money become a tool for helping others?
Legacy could mean:
- supporting children
- helping family
- charitable giving
- teaching financial habits
- creating a business
- supporting a community
- leaving behind values rather than just assets
The final lesson is therefore deeply personal:
Wealth isn’t the destination. It’s a tool.
Real-Life Example 2: Scott Pape and Liz’s “Serviette Strategy”
One of the most useful real-life examples is Scott Pape’s own household.
Pape describes sitting down with his wife Liz and creating their money system on a restaurant serviette.
They identified three priorities:
- financial security
- enjoying travel and experiences
- building long-term wealth so they could eventually work less
They then organized their money around the three buckets. Pape says the strategy helped them manage goals including an investment property, honeymoon savings, mortgage repayment, a business with irregular income and an emergency fund.
The lesson is not that every household should copy their exact percentages.
The lesson is:
A financial system becomes powerful when it is simple enough to use in real life.
The Barefoot Benchmark: Learn to Live Below Your Income
One of the most important practical ideas associated with the system is controlling everyday spending.
The published explanation of the Barefoot method uses a benchmark in which regular expenses are kept around 60% of take-home income, with other portions directed toward enjoyment, longer-term goals and financial problems.
The exact percentages shouldn’t be treated as universal laws.
For someone in Mumbai, Delhi, Bengaluru or Nagpur, housing costs may be completely different from those in Australia.
Instead, take the principle:
Don’t allow lifestyle inflation to consume every increase in income.
If your income rises, don’t automatically increase every expense.
Let part of the increase improve your financial future.
A Step-by-Step Barefoot Action Plan for Your Own Life
Step 1: Have Your Money Meeting
Sit down alone or with your partner.
Write down your three biggest financial goals.
Step 2: Calculate Your Monthly Take-Home Income
Know the actual amount available after taxes and mandatory deductions.
Step 3: Track Your Essential Expenses
List:
- housing
- food
- transport
- utilities
- insurance
- education
- other essential costs
Step 4: Create Separate Money Buckets
Use the Barefoot philosophy as a framework:
Spend → Safety → Grow
Adapt the accounts and percentages to your country and circumstances.
Step 5: Create a Fun-Money Category
Don’t make your financial plan so restrictive that you eventually abandon it.
Give yourself controlled spending money.
Step 6: Build Your Emergency Fund
Start with a small target.
Then gradually build toward several months of essential living expenses.
Step 7: List Every Debt
Don’t hide from debt.
Write down every balance and interest rate.
Step 8: Attack High-Cost Debt
Create a deliberate repayment plan.
As one debt disappears, redirect that cash flow toward the next financial goal.
Step 9: Build Long-Term Investments
Once your foundation is strong, direct money toward appropriate long-term investments.
Step 10: Review Your Progress Monthly
Ask:
What improved?
What went wrong?
What will I change next month?
Small improvements compound too.
10 Biggest Takeaways From The Barefoot Investor
1. Give every rupee a job.
Money without a purpose tends to disappear.
2. Automate good financial behavior.
Don’t rely entirely on willpower.
3. Separate spending from saving.
Physical and mental separation can make financial discipline easier.
4. Enjoy some of your money.
Financial discipline shouldn’t mean eliminating happiness.
5. Destroy expensive debt.
Debt can consume future income.
6. Build emergency savings.
Savings create financial flexibility and reduce dependence on debt.
7. Invest for the long term.
Wealth building is a process, not a quick event.
8. Plan your retirement.
Don’t leave your future financial security to chance.
9. Talk about money.
Healthy financial communication can improve household decision-making.
10. Use wealth to create freedom and impact.
Money is a tool for living a meaningful life—not simply a score to maximize.
The official Barefoot Steps reinforce this progression from money organization and debt management toward home ownership, superannuation, emergency savings, mortgage reduction, retirement and legacy.
What Makes The Barefoot Investor Different?
There are thousands of books about investing.
Many discuss:
- stock markets
- asset allocation
- compound interest
- financial theory
- economic cycles
The Barefoot Investor takes a different starting point.
It asks:
How do ordinary people actually behave with money?
Because knowing what to do isn’t enough.
You need a system you can follow when:
- you’re tired
- you’re busy
- you want to spend
- your income changes
- an emergency appears
- the market falls
- life gets complicated
That’s why the bucket system is so memorable.
It turns abstract financial planning into something visible.
Blow. Mojo. Grow.
You can imagine the money moving.
You can see whether you’re progressing.
And you can make the next decision more easily.
The Deeper Lesson: Financial Freedom Is Not About Becoming Rich Overnight
Imagine someone earning ₹5 lakh a month but spending ₹5 lakh.
Now imagine another person earning ₹1 lakh but consistently saving, protecting and investing part of it.
Who is building financial freedom?
The answer isn’t determined by income alone.
It’s determined by what happens to the income after it arrives.
This is perhaps the most important lesson of The Barefoot Investor.
You don’t need to wait until you’re wealthy to start behaving like someone who is financially organized.
You can begin now.
With the income you have.
With the expenses you currently face.
With the debts you’re currently carrying.
With small amounts.
The system grows with you.
Final Thoughts: Don’t Just Earn Money—Build a System for Your Money
At the end of the day, financial freedom isn’t created by one perfect investment.
It is built through hundreds of ordinary decisions.
You decide to save.
You decide not to take unnecessary debt.
You decide to build an emergency fund.
You decide to invest.
You decide to control lifestyle inflation.
You decide to talk honestly about money.
You decide to plan for retirement.
And eventually, you decide what your money is actually for.
Scott Pape’s nine-step framework provides a practical sequence: organize your money, build the buckets, tackle debt, think about housing, strengthen retirement savings, build emergency reserves, reduce mortgage debt, determine your retirement target and ultimately think about legacy.
That is why The Barefoot Investor remains such a useful personal-finance framework.
It doesn’t tell you that money will always be easy.
It tells you that money can become organized.
And when money becomes organized, something remarkable happens.
You stop asking:
“Where did all my money go?”
And start asking:
“How can I make my money work toward the life I want?”
That is a much better question.
And sometimes, a better question is the beginning of a completely different financial life.
Book to Life: Turn The Barefoot Investor Into Your Life
The purpose of the Book to Life series isn’t simply to summarize books.
It is to take ideas from books and bring them into everyday life.
So don’t try to implement everything at once.
Start with one step.
Tonight, write down your income and expenses.
Tomorrow, create your first savings bucket.
This week, list your debts.
This month, build your first emergency-fund target.
Then gradually move toward investing and long-term wealth creation.
Your financial transformation doesn’t have to begin with a huge amount of money.
It can begin with one organized account, one better habit and one decision to take control.
Read The Barefoot Investor.
Study the system.
Adapt the concepts to your own country and circumstances.
And most importantly:
Put the book down and put the lesson into action.
Because a financial book can teach you how money works.
But only your actions can change your financial life.